
Physical needs, reserves and the CNA e-Tool
Capital Needs Assessment for HUD Multifamily Properties
A component-by-component survey of what your property is made of, how much life each part has left, and what it will cost when that life runs out. The document lenders require and owners should want anyway.
The lump sum funded at closing, sized to cover what the schedule says is coming before annual deposits can accumulate.
The recurring figure, set so the reserve funds each scheduled replacement at the point the schedule expects it.
What a CNA is
A twenty-year cost forecast, built from what is actually there
A capital needs assessment is a detailed survey of every major building component, judging the present condition and remaining useful life of each, then converting that into a twenty-year schedule of replacement costs and the reserve deposits needed to fund them.
It answers questions guesswork cannot. When the roof needs replacing rather than repairing. Whether the boilers survive the loan term. How much to set aside each year so those events are budgeted rather than borrowed for.
For HUD and FHA multifamily lending it is not optional. Applications under 221(d)(4), 223(f), 223(a)(7) and 232 all require one, and submissions run through HUD's CNA e-Tool, the standardised platform for preparing and reviewing assessments. Use of the e-Tool has been mandatory since February 2018 for FHA multifamily mortgage insurance applications, RAD conversions and ten-year update assessments on FHA-insured properties.
Condition ratings and life expectancy are not judged freehand. The assessment works from HUD's Estimated Useful Life table, published in Housing Notice 2016-18, which sets the baseline lifespan for each component category. That is what makes one assessor's twenty-year schedule comparable to another's.
A CNA is a condition survey, not a compliance survey, so it does not replace inspection readiness. Where it turns up items that would also score, our inspection services assess them against the NSPIRE standards and our repair services correct them. A component with eight years of life left can still be a scored deficiency today, which is why REAC consulting and a CNA answer different questions, and why preventive maintenance protects the reserve schedule a CNA sets out.
Owners who commission a CNA and an inspection survey together usually pay less than for two separate site visits.
Three names, three documents
CNA, PNA and PCA are not interchangeable
People use these terms as though they mean the same thing, and then find out at submission that the wrong one was commissioned. The difference is which programme is asking and what format the answer has to arrive in.
Capital needs assessment
The HUD and FHA multifamily document. Twenty-year component schedule, prepared and submitted through the CNA e-Tool against HUD's Estimated Useful Life table, producing the replacement reserve deposits.
FHA insured, RAD, HUD asset management
Physical needs assessment
The public housing equivalent, sitting under the Capital Fund rather than under FHA lending, with its own planning period and its own energy audit requirements under 24 CFR 905. Often paired with an energy audit as a green PNA.
Public housing authorities
Property condition assessment
The conventional market version, used by commercial lenders, buyers and insurers. Similar survey work, no HUD format, no e-Tool submission, and no prescribed useful life table behind the numbers.
Conventional lending, acquisitions
Not sure which one your programme actually requires? That is a five-minute conversation, not a proposal.
The deliverable
What the e-Tool submission actually contains
A CNA is not a report with a cover page. It is a structured submission in two parts, and the second part is where the money is decided.
The narrative
A description of every component and its present condition, recorded against the standard categories. Depending on the programme this may also carry an energy audit.
- Component-level condition and remaining useful life
- Immediate needs separated from scheduled needs
- Contact detail for owner, lender, assessor and any intrusive testing
- Photographic record supporting each finding
The financial model
The twenty-year capital reserve table, broken out by component group, and the two reserve deposit figures HUD and your lender will actually read.
- Site systems
- Mechanical, electrical and plumbing
- Structural
- Common areas
- Life safety systems
- Apartment units
An assessment that overstates remaining life produces a reserve that will not cover what happens. One that understates it costs you money every year for twenty years. That is the whole reason the useful life table exists, and the reason a schedule built freehand does not survive review.
The process
Key components of our capital needs assessment
Property inspection
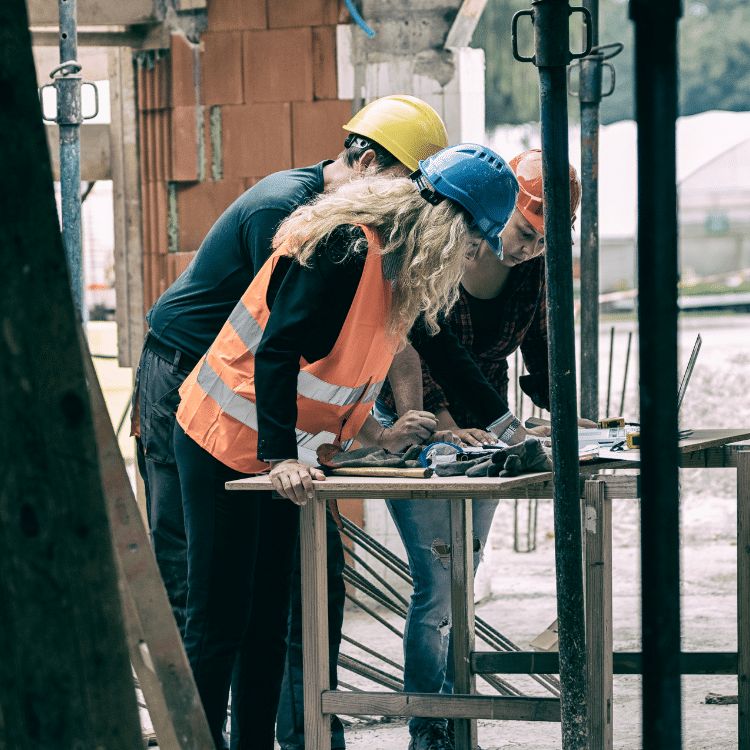
A full walkthrough of every major system, from roof to foundations to plumbing, documenting the present condition of each component rather than sampling and extrapolating.
Component life analysis
Every element has a lifespan. We judge how much of it remains against HUD's useful life benchmarks, separating what needs attention now from what can be scheduled, and when.
Cost projections
Costed estimates for immediate repairs and for each scheduled replacement, so the forecast is a budget you can act on rather than a list of concerns.
Reserve deposit figures
The initial and annual deposits derived from the schedule, set to satisfy HUD and lender review while genuinely covering what is coming.
Why lenders insist
The CNA protects the lender, and it protects you
A lender underwriting a thirty-year mortgage needs to know the building will still be standing and lettable in year twenty. The CNA is how that gets established: documented condition, remaining life, and a funded plan for the gap.
The same document does something for you that has nothing to do with financing. It converts capital spending from a series of emergencies into a schedule. A roof replaced on plan costs a fraction of a roof replaced after it fails, and a well-evidenced assessment strengthens an application rather than merely satisfying it.
- Required for 221(d)(4), 223(f), 223(a)(7) and 232 applications
- Prepared and submitted through HUD's CNA e-Tool
- Mandatory for RAD conversions and financing plan submissions
- Ten-year updates required across the life of an FHA-insured loan
- Sets the initial and annual replacement reserve deposits
Choosing a provider
What to ask any capital needs assessment provider
A CNA is prepared by a needs assessor and submitted through the e-Tool by a submitter, usually the lender, a participating administrative entity or the housing authority, with HUD as the approving agency. Knowing who fills which role on your transaction saves a fortnight of confusion.
How much of the property gets seen
The e-Tool protocol sets a minimum sample rather than leaving it to judgement, covering a proportion of apartments in each building and a proportion of each unit type. Ask what will actually be walked, and put every unit on notice.
Which useful life table is used
If the answer is not HUD's published table, the schedule will not survive review. Comparable numbers are the entire point of a standardised submission.
Who submits, and who signs
Preparer and submitter are separate roles in the e-Tool and are sometimes the same party. Establish which applies to your programme before work starts, not at submission.
What happens when review comes back
Submissions get queried. Ask whether responding to the approving agency is included or billed separately, because that exchange is often where a timeline slips.
We will answer those four questions about our own process before you ask them.
Timing
The CNA is usually the long lead item
Assessments have a shelf life, and financing calendars do not move. Working backwards from the submission date is the only sensible way to plan it.
Within 180 days
For a RAD conversion, the CNA has to be submitted with the financing plan and generally completed no earlier than 180 days before that submission, absent HUD approval. An assessment done too early has to be redone.
Site visit
One to two days on site for most properties, depending on unit count and how spread out the buildings are. We can often be on site within 24 hours, so the survey itself is rarely what holds up a submission.
Report and model
A few weeks from the site visit to a validated e-Tool submission, covering both the narrative and the twenty-year financial model.
Every ten years
Update assessments across the life of an FHA-insured loan, plus a fresh assessment with any new application.
On the day
What to expect during your assessment
We schedule the visit, arrive with everything needed, and survey the property in one pass. Access is the thing that most often costs a day, so unit notices go out ahead of us rather than on the morning.
After the walkthrough the findings are compiled into the narrative and the financial model. What you receive is a submission your lender can take forward and a schedule your own team can work from.
- Roofing, exterior surfaces and structure
- Plumbing, electrical and mechanical systems
- HVAC equipment and ventilation
- Common areas and unit interiors
- Site conditions and accessibility features
- Safety and code compliance items
Assessed components
What the survey covers
Each component judged for present condition and remaining useful life. The framework follows HUD's CNA e-Tool standards, including its estimated useful life benchmarks.
Financing application coming? The CNA is usually the long lead item.
Questions
Capital needs assessment FAQs
What is a capital needs assessment?
A detailed survey of every major building component, judging present condition and remaining useful life, then converting that into a twenty-year schedule of replacement costs and the reserve deposits needed to fund them.
For HUD and FHA multifamily properties it is prepared and submitted through the CNA e-Tool, and the schedule is built against HUD's published Estimated Useful Life table so that one assessment is comparable to another.
What is the difference between a CNA, a PNA and a PCA?
A CNA is the HUD and FHA multifamily document, submitted through the e-Tool. A PNA is the public housing equivalent, sitting under the Capital Fund with its own energy audit requirements. A PCA is the conventional market version used by commercial lenders and buyers, with no HUD format behind it.
The survey work overlaps heavily. The format, the useful life table and the submission route do not, which is why commissioning the wrong one is an expensive mistake to discover late.
How often do I need one?
HUD and FHA programmes generally require an update about every ten years across the life of the loan, and a fresh assessment with any new application.
Outside that requirement, owners often commission one before a sale or a major financing decision because it is the cheapest way to know what you are actually holding.
How long does the process take?
On-site work is usually one to two days depending on unit count and how many buildings there are, with the report and financial model following within a few weeks.
We can often be on site within 24 hours. Access arrangements, not survey time, are the usual constraint.
How current does the assessment have to be at submission?
For a RAD conversion the CNA is submitted with the financing plan and generally has to have been completed no earlier than 180 days before that submission, unless HUD approves otherwise.
That cuts both ways: commissioning too late delays the plan, and commissioning too early means paying for it twice. Tell us the submission date and we will work backwards from it.
Can a property fail a CNA?
No, and that is worth understanding. A CNA does not pass or fail anything. It records condition, remaining life and cost.
If it surfaces significant problems, you get them costed and scheduled, which is far better than discovering them later. What it can do is produce reserve deposits large enough to affect how a transaction pencils, which is a different kind of bad news and one worth knowing early.
What are IDRR and ADRR?
The initial deposit to replacement reserve and the annual deposit to replacement reserve. The first is funded at closing, the second recurs for the life of the loan.
Both come out of the twenty-year schedule, which is why the condition and life judgements made during one site visit end up on your operating budget for two decades.
Do I need one if I am not a HUD property?
Not required, but the value does not depend on the programme. Any owner benefits from knowing when each system needs replacing and what to reserve.
Conventional lenders and buyers ask for the same thing as a property condition assessment. We can scope it either way.
What does it cost?
Unit count, building count and geography drive it, which is why nobody can quote sensibly without those three numbers.
What we can say is that it is small relative to a single unplanned major replacement, which is the expense a CNA exists to prevent.
Is a CNA the same as an inspection readiness survey?
No. A CNA looks at condition and cost over twenty years. An inspection survey looks at whether items meet published standards today.
They overlap but answer different questions, so if you need both, say so and we will scope them together rather than surveying the property twice.